Executive Summary
Repositioning Capital One Spark for Small Business Growth
Company
Capital One
Timeline
3 months
Project
Research, IA, & CX
My Role
Creative Director
The Problem
Capital One launched Spark as a new small business product line, but:
- Customers perceived Spark as repackaged consumer banking products
- The digital experience did not reflect the realities of small business ownership
- Capital One lacked a clear understanding of how SMB owners think about managing their finances
Without differentiation, Spark risked blending into a crowded market.
Outcome
- Validated how small business owners evaluate financial tools and make decisions
- Narrowed the target to businesses under $2M in revenue and under ten years old, the owners most open to switching banks
- Developed multiple site architecture concepts aligned to SMB motivations
- Delivered two marketing-site architectures (product-led and needs-led) and a signed-in dashboard built around the three questions owners ask first
My Role
- Creative Director and Account Lead
- Led qualitative research with small business owners
- Synthesized 11 interviews, card sorts, and stack ranking into six principles for the site and the signed-in experience
- Directed the two site architectures and the dashboard concept presented to Capital One’s executives
Detailed Case Study
Research
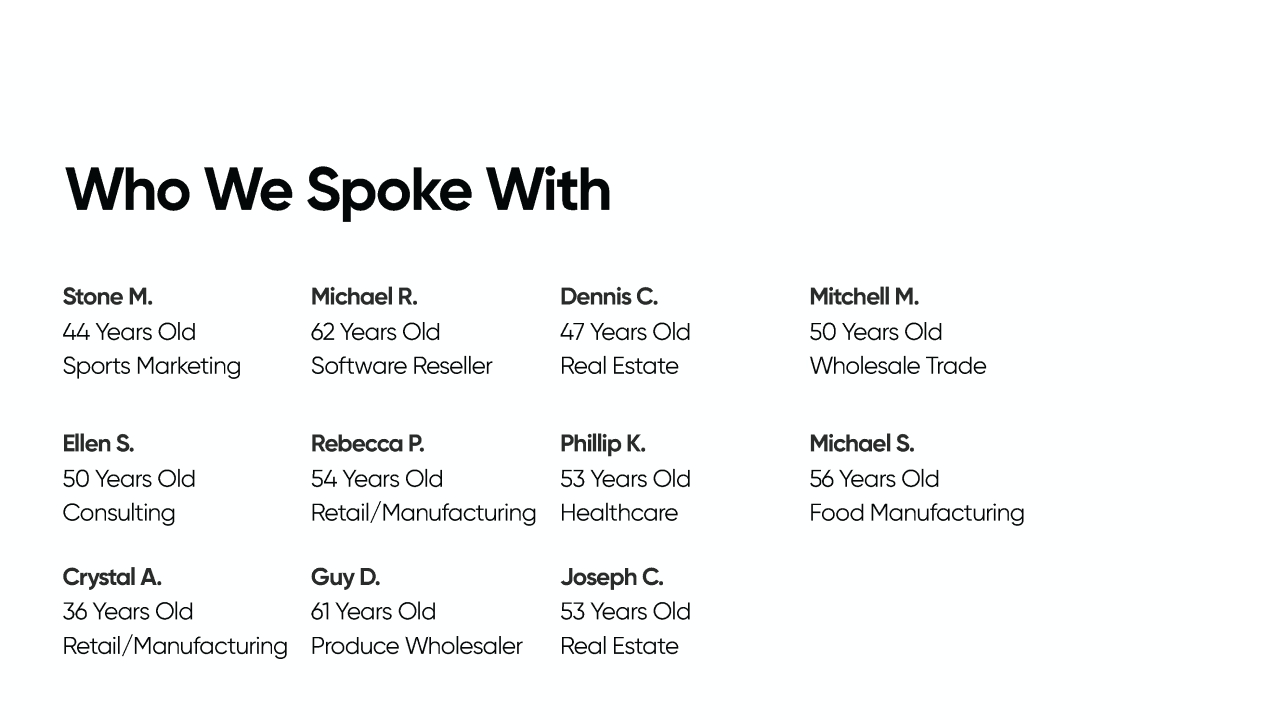
In-Depth Interviews (11 Participants)
Conducted in-depth interviews with 11 small and medium business owners across industries to observe how they:
- Track revenue and expenses
- Manage short-term cash flow
- Make decisions about financial tools
Behavioral Exercises
To uncover mental models beyond verbal responses, we incorporated:
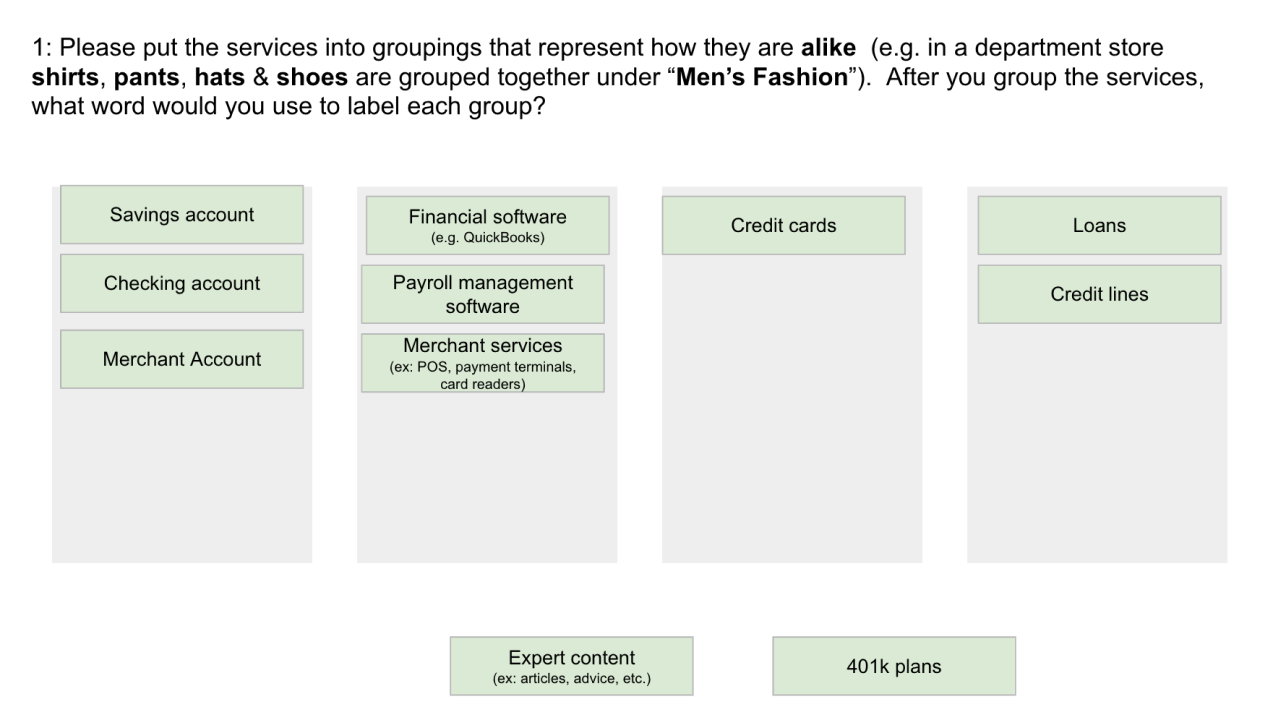
- Card sorting exercises to understand categorization logic
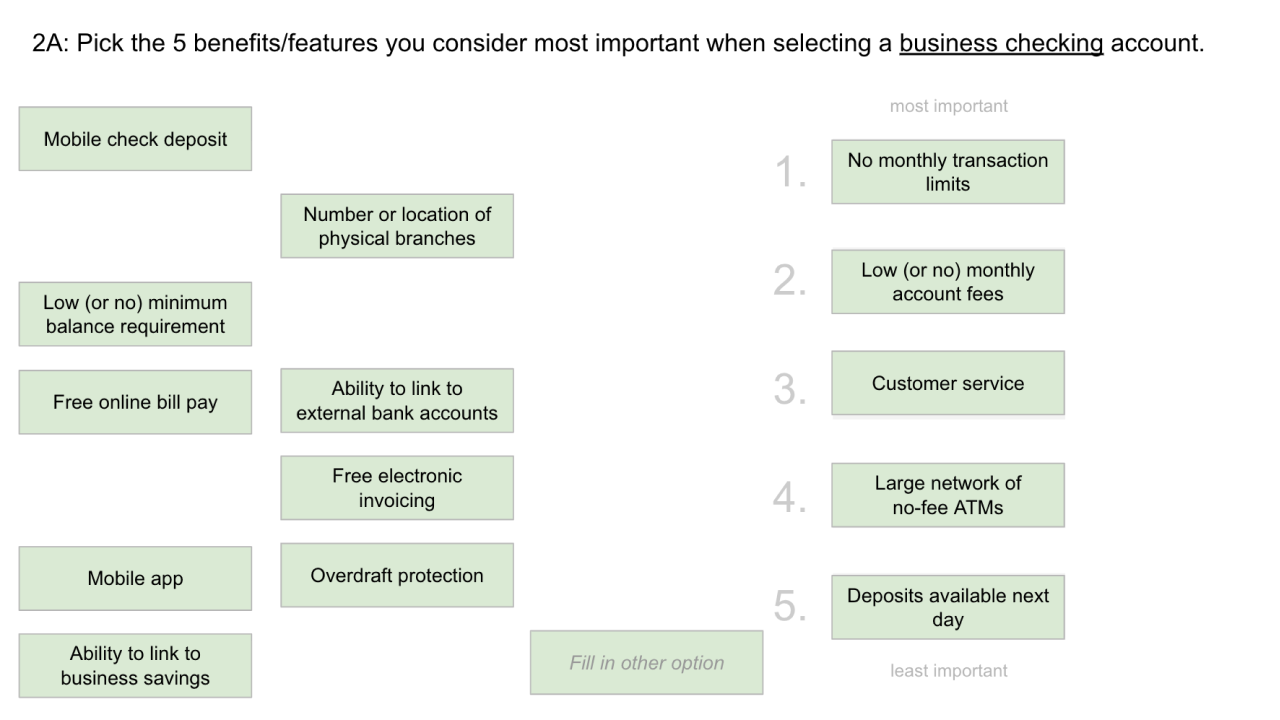
- Stack ranking to identify priority needs and decision drivers
Card Sorting
Stack Ranking
Insights
Target Audience Definition
Research clarified the specific small business segment Spark was best positioned to pursue. The most aligned audience consistently shared three primary characteristics:
- Digital Savvy: Conducts the majority of banking online, yet still values access to a real person to quickly resolve complex issues or build a trusted relationship.
- Small and Growing Businesses: Typically less than 10 years old and actively expanding. More mature, established companies showed less likelihood of increasing financial complexity or switching providers.
- Under $2 Million in Annual Revenue: Businesses above this threshold were significantly less likely to change banks or shop for new financial products. Companies under $2M demonstrated greater openness to new accounts and money-saving opportunities.
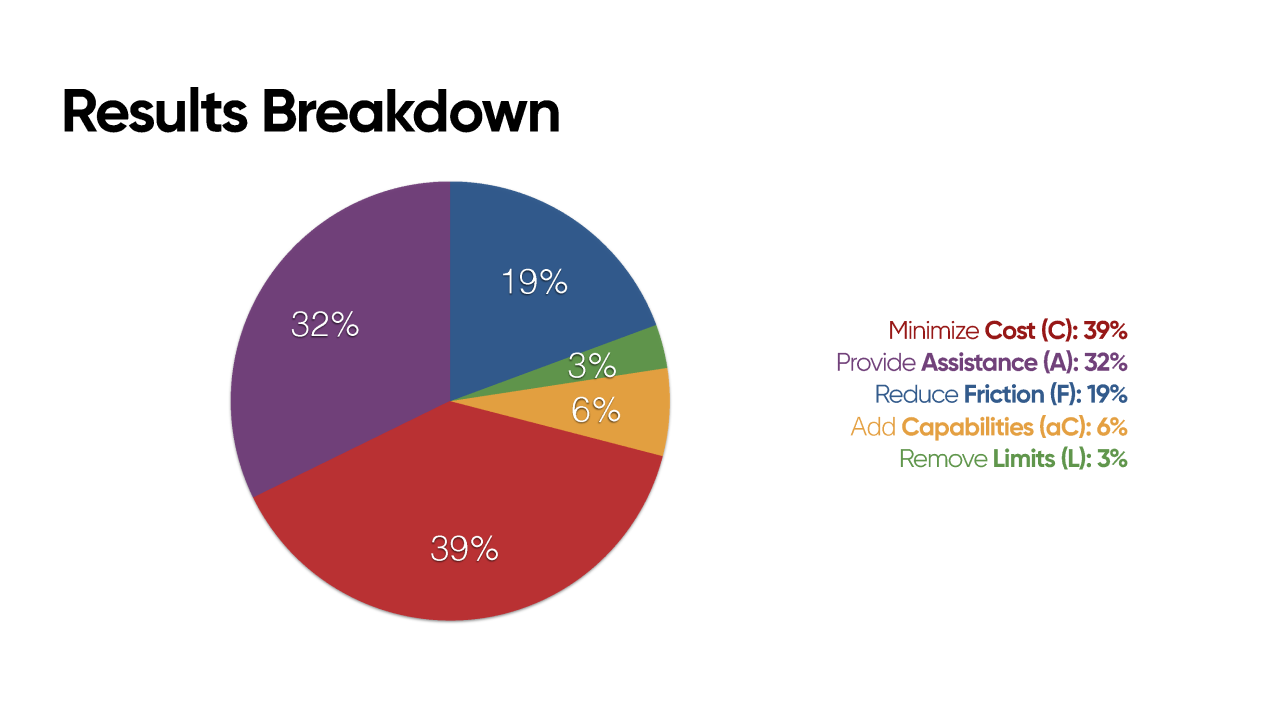
What SMB Owners Want Most From Their Bank
The highest-priority needs were keeping costs low and getting help when needed.
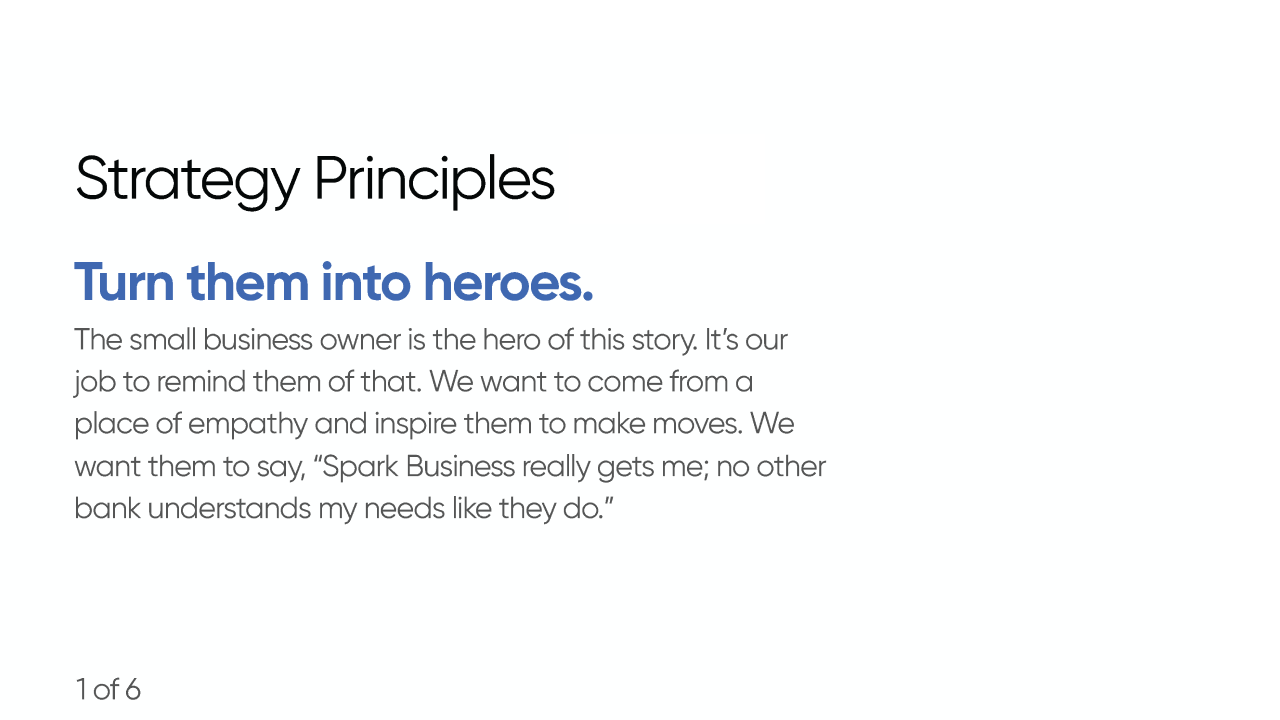
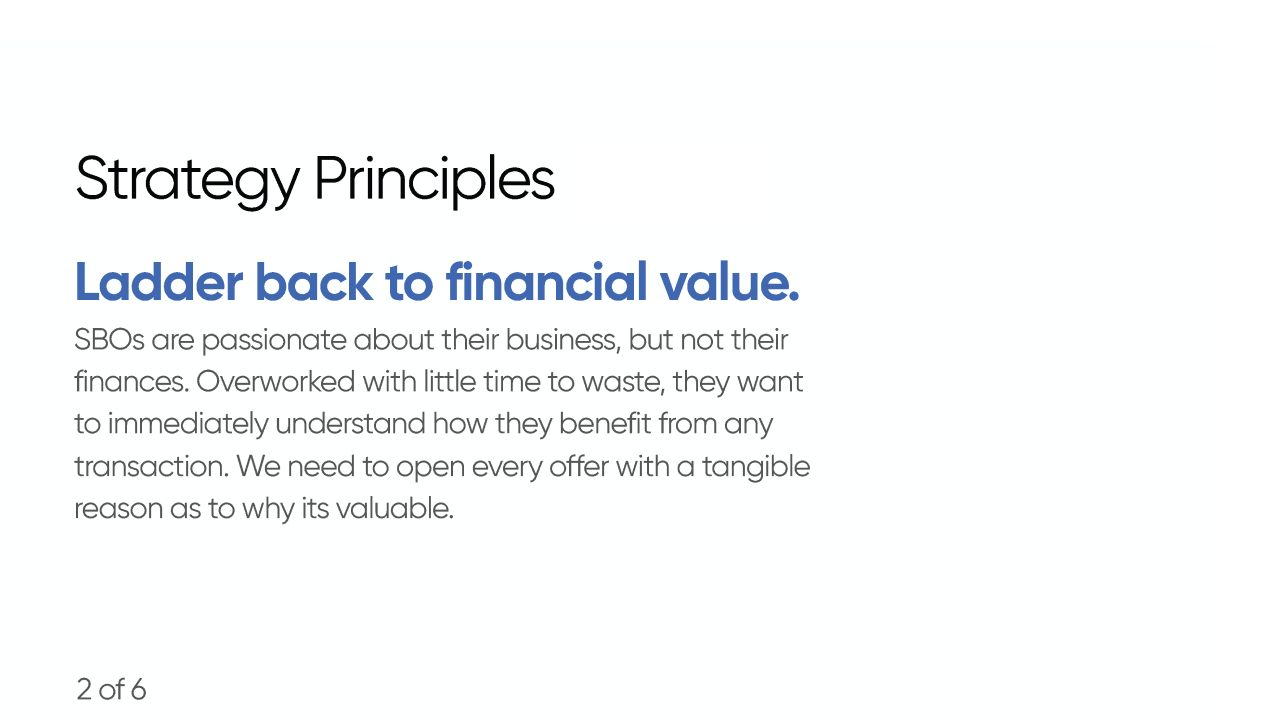
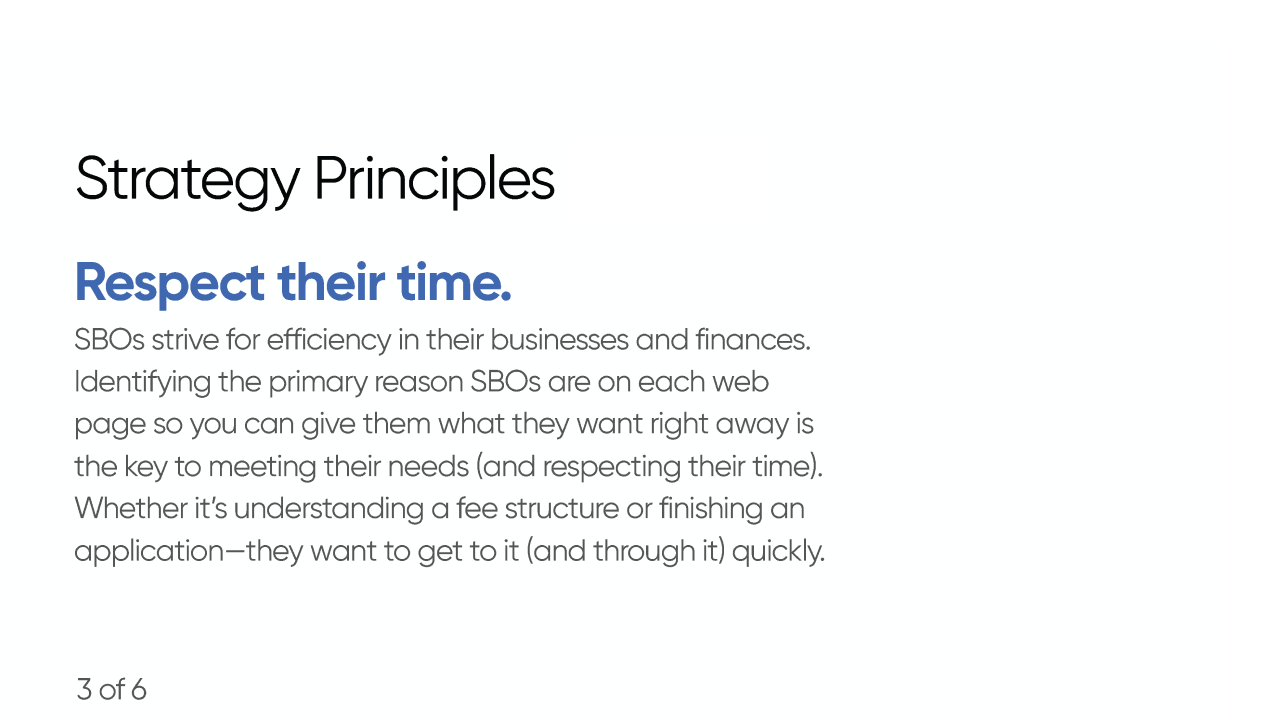
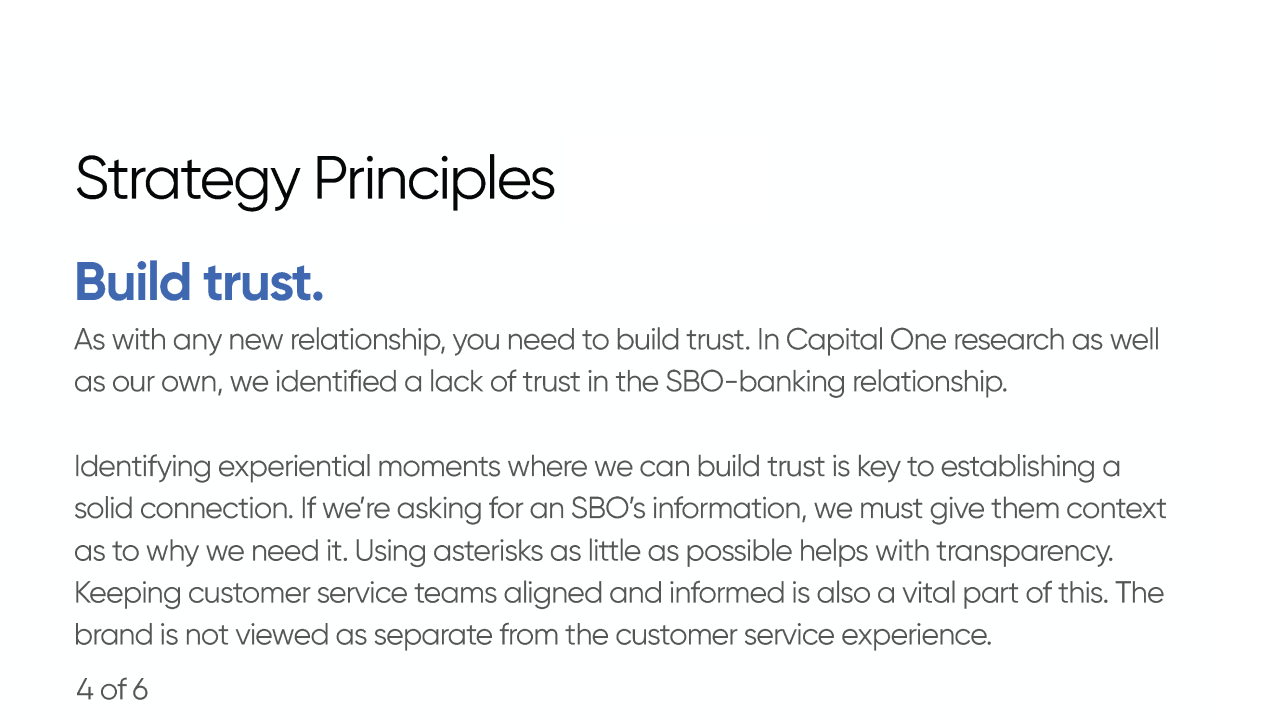
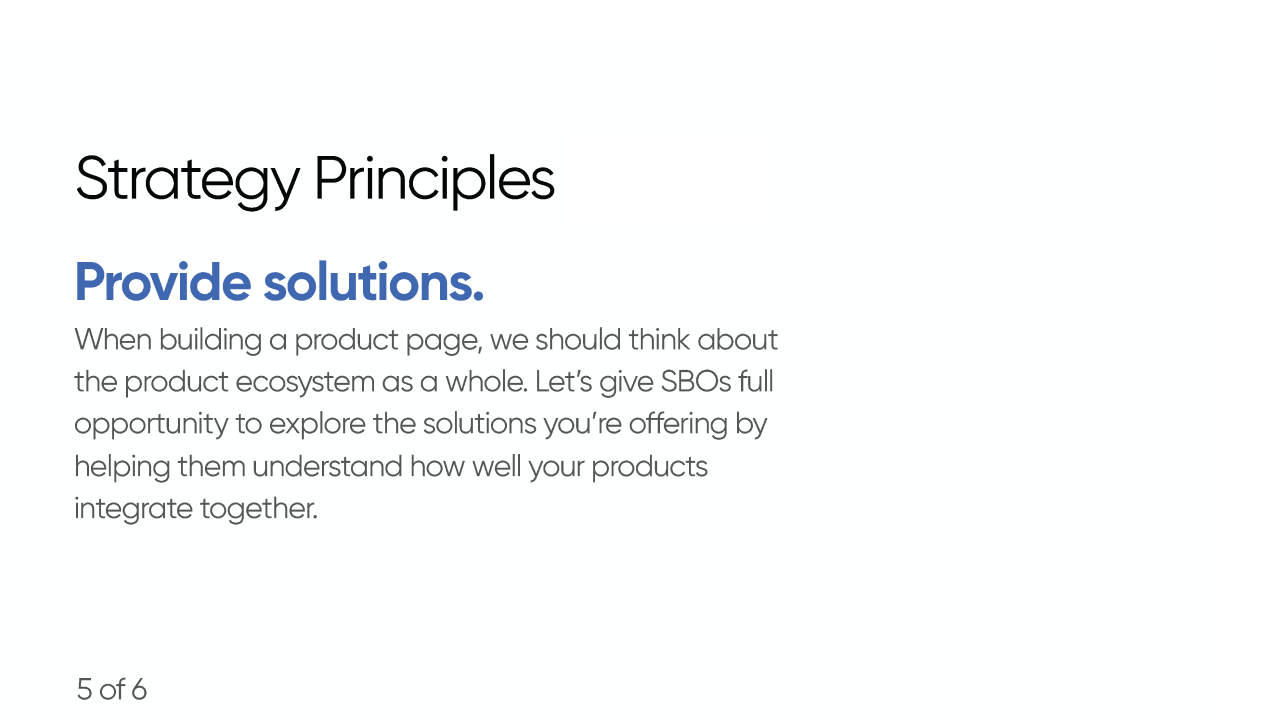
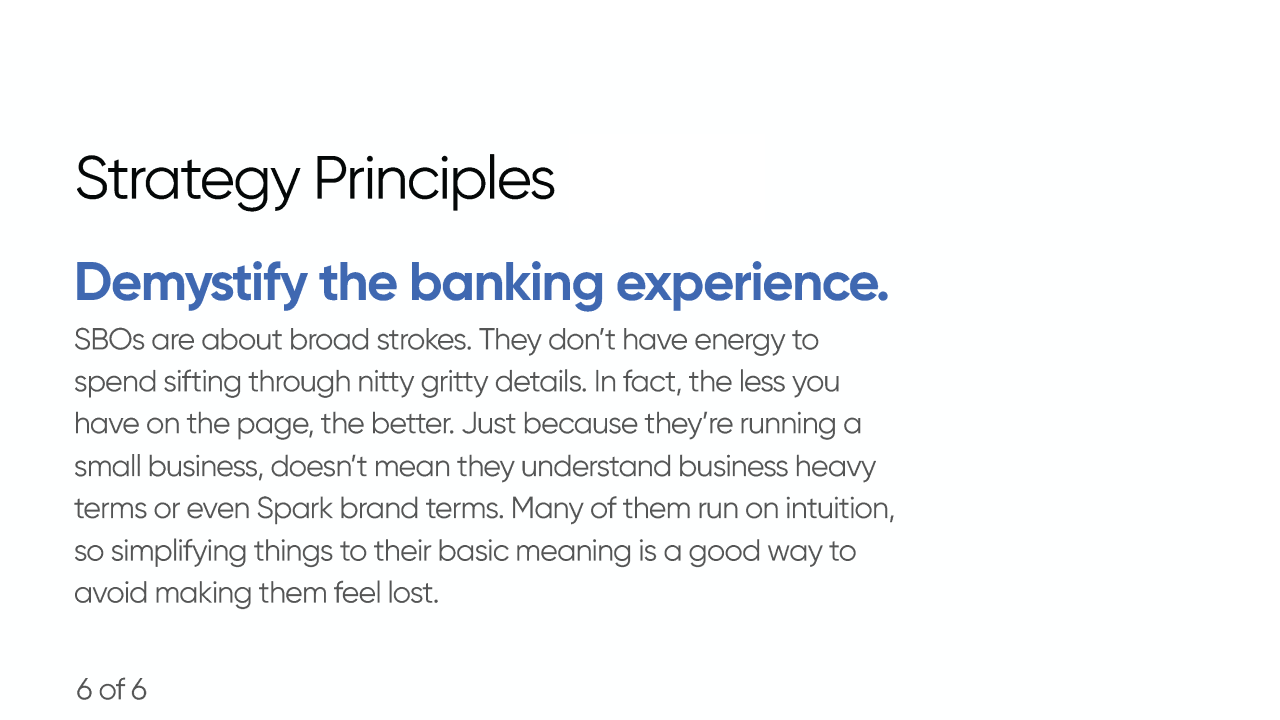
Six Strategy Principles
The research informed six guiding principles that shaped both the marketing site and signed-in experience.
Marketing Website Concepts
Research revealed a split in how small business owners think:
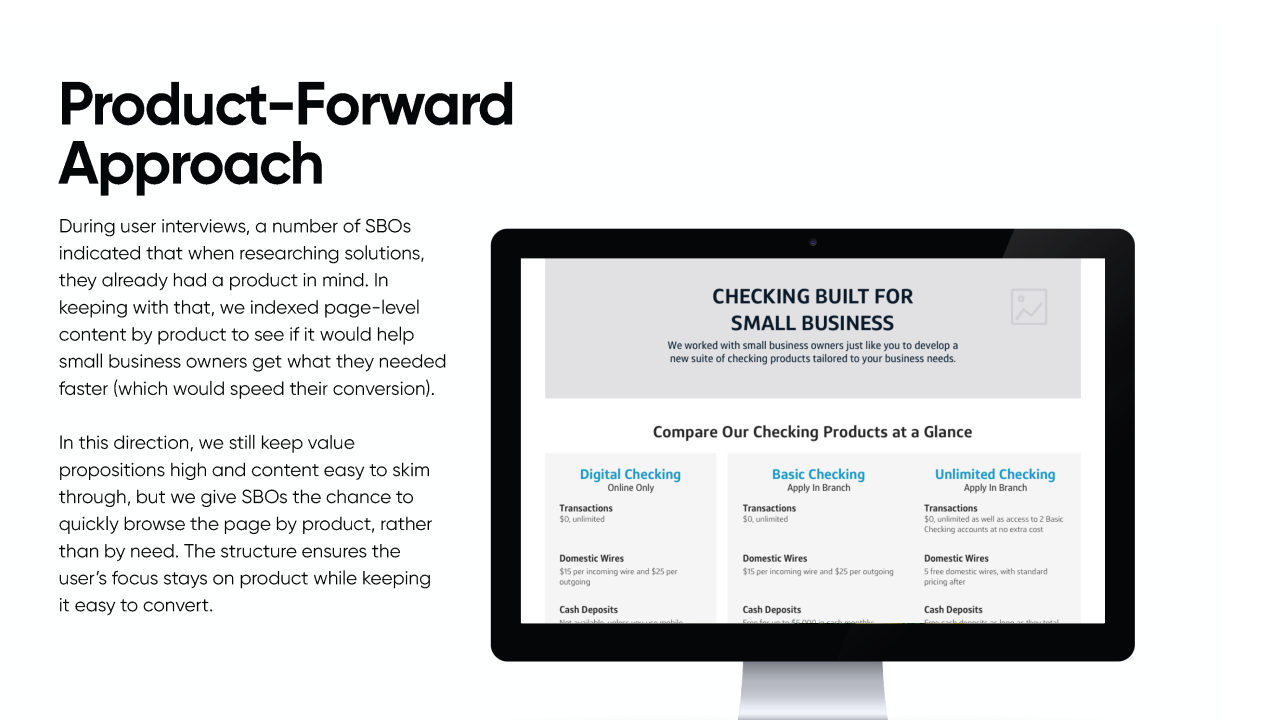
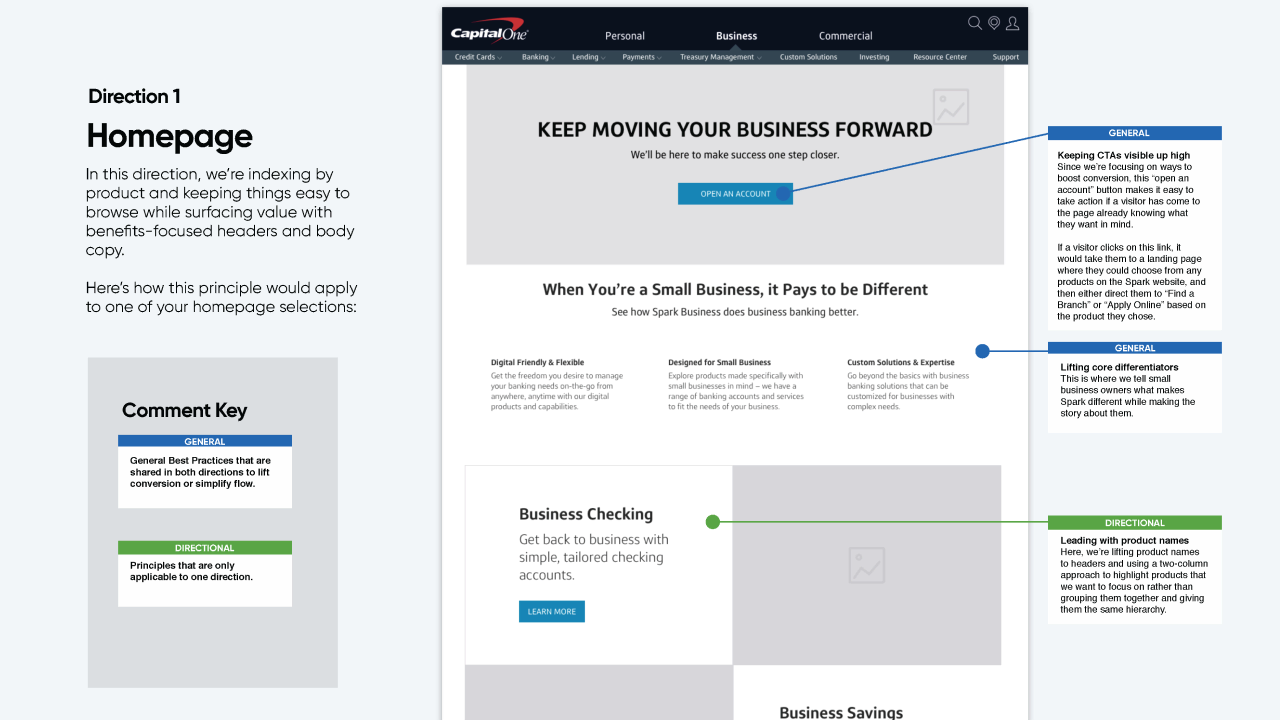
- Some approach banking in terms of products (credit card, checking, etc.).
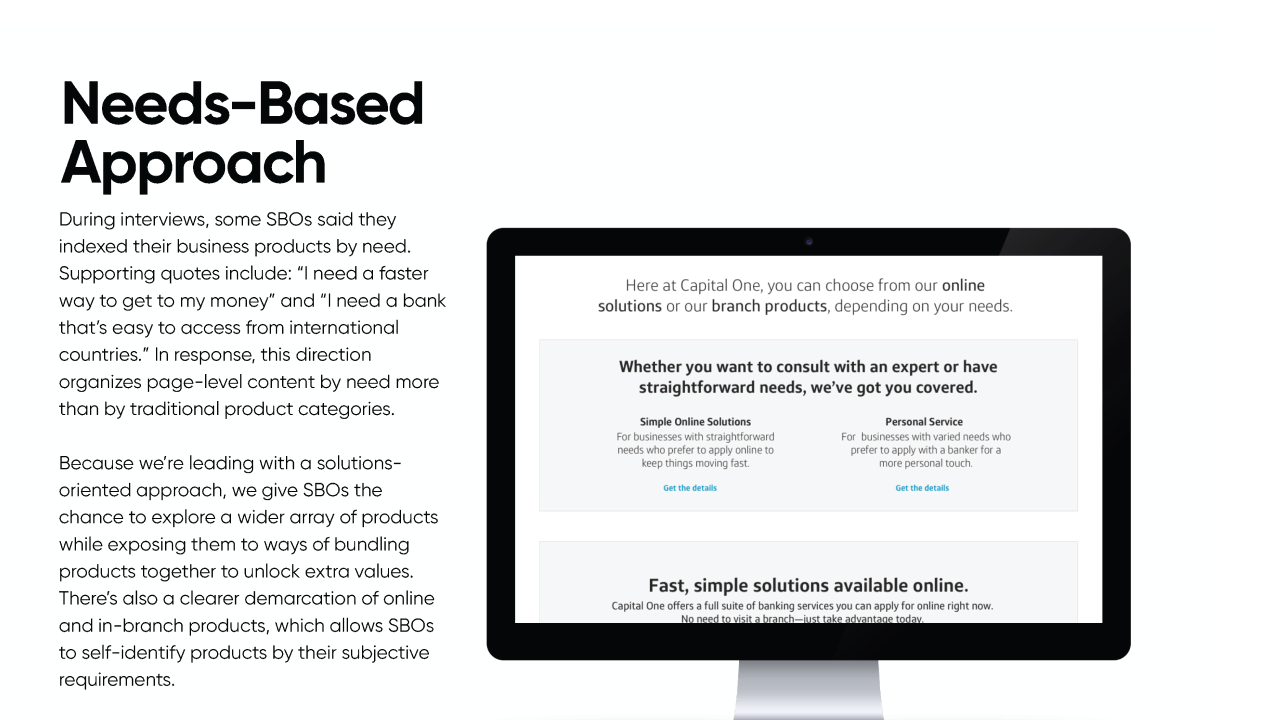
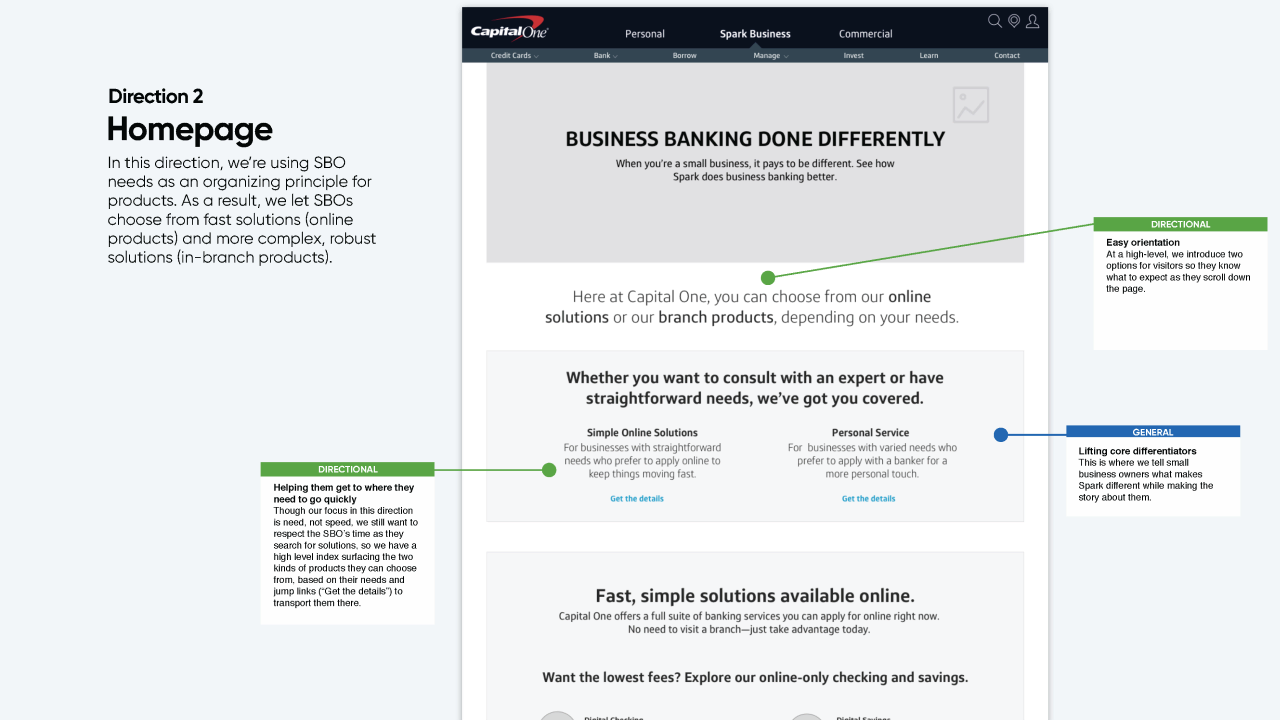
- Others think primarily in terms of needs (manage cash flow, control expenses, grow revenue).
To reflect this divide, we developed multiple information architecture directions:
Direction 1: Product-Led
Direction 2: Needs-Led
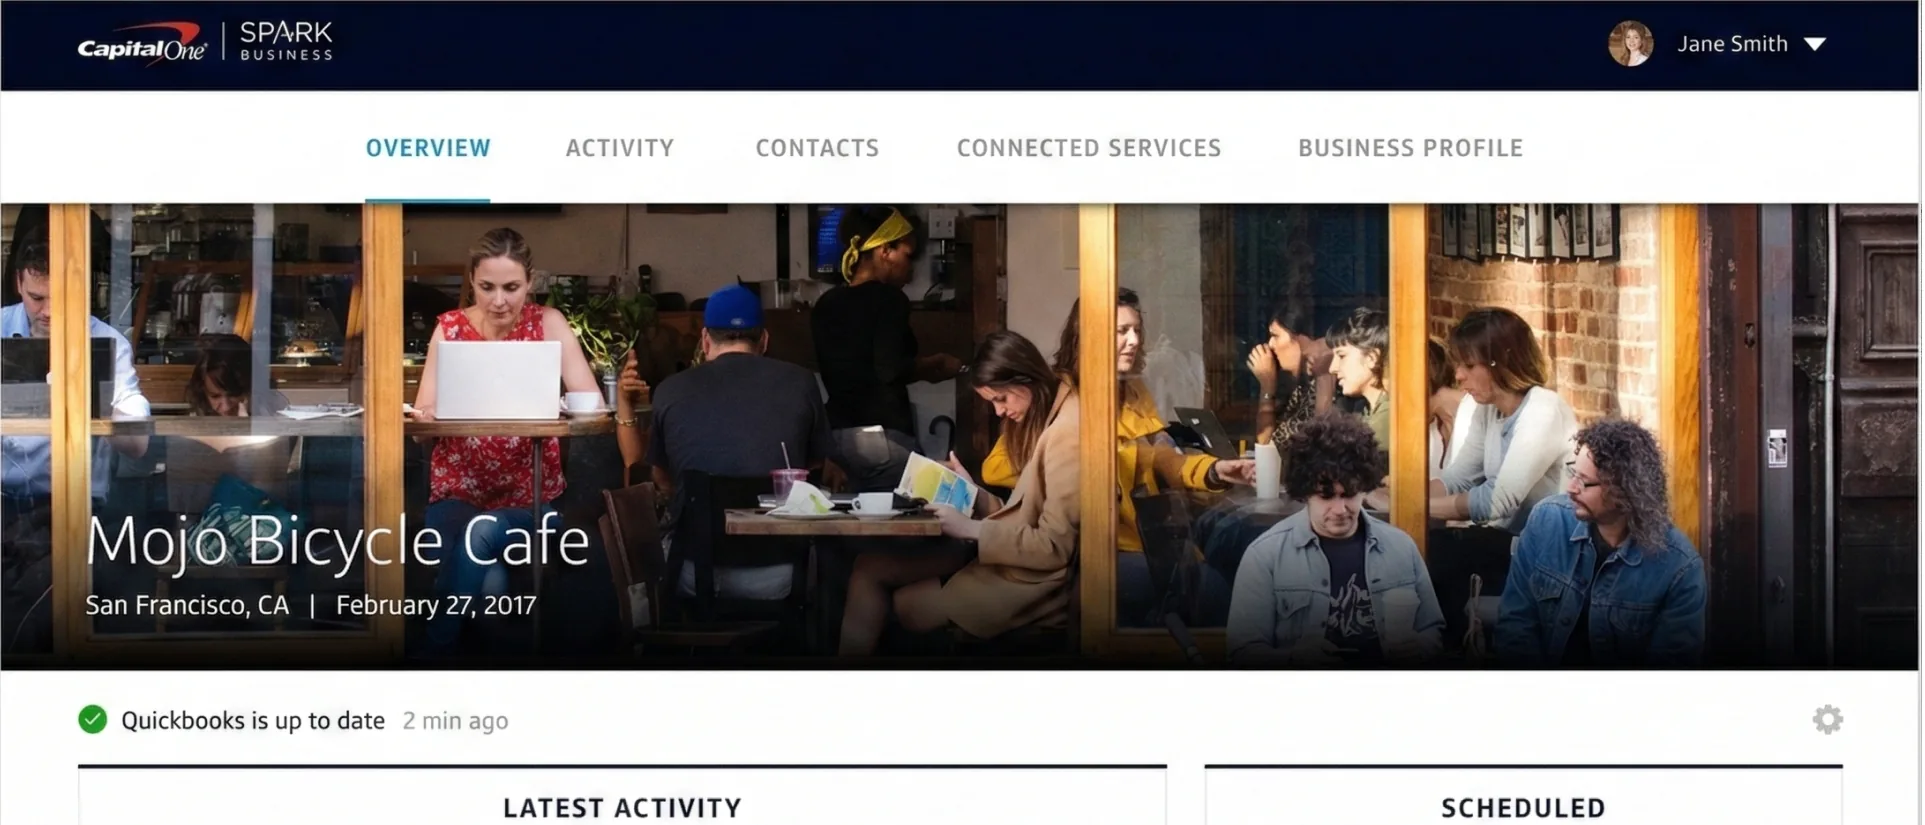
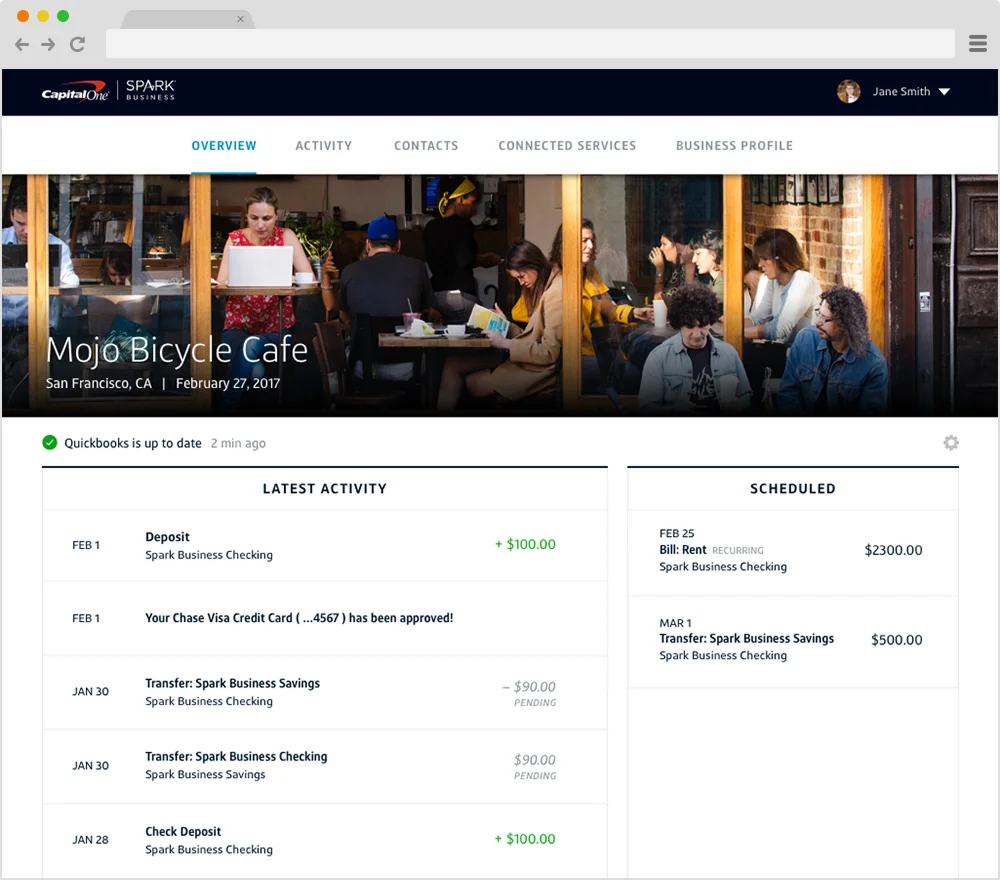
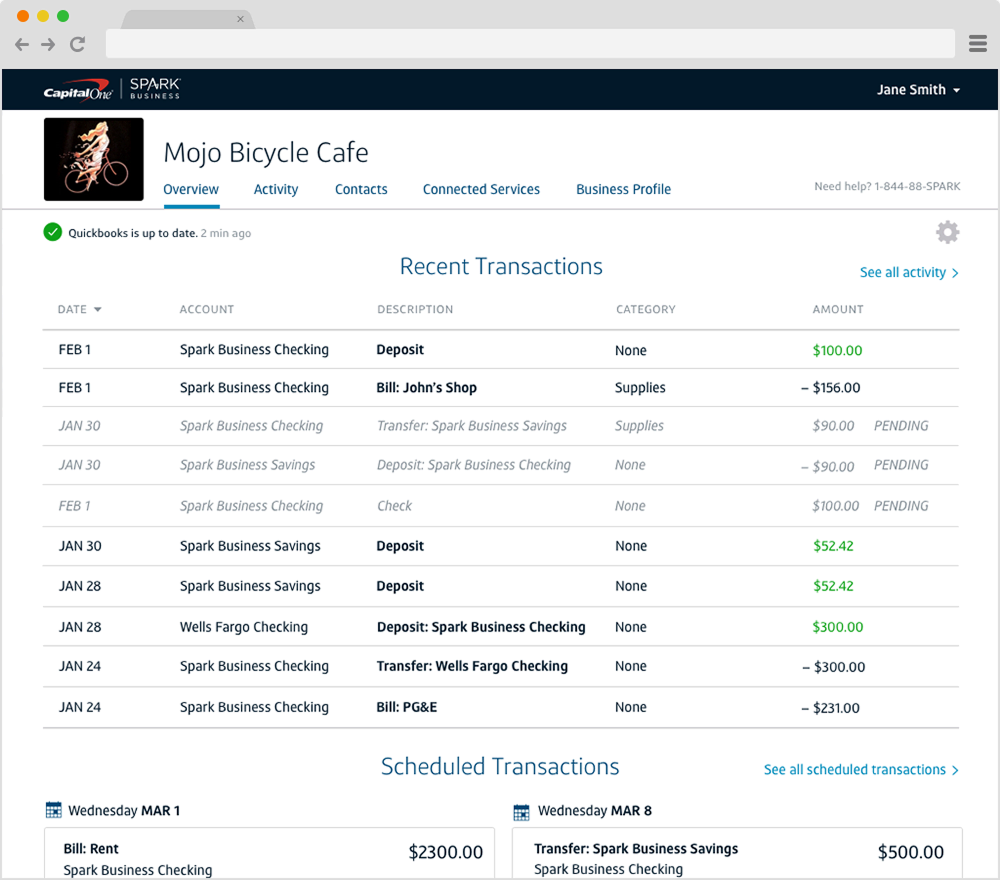
Signed-In Spark Dashboard Concept
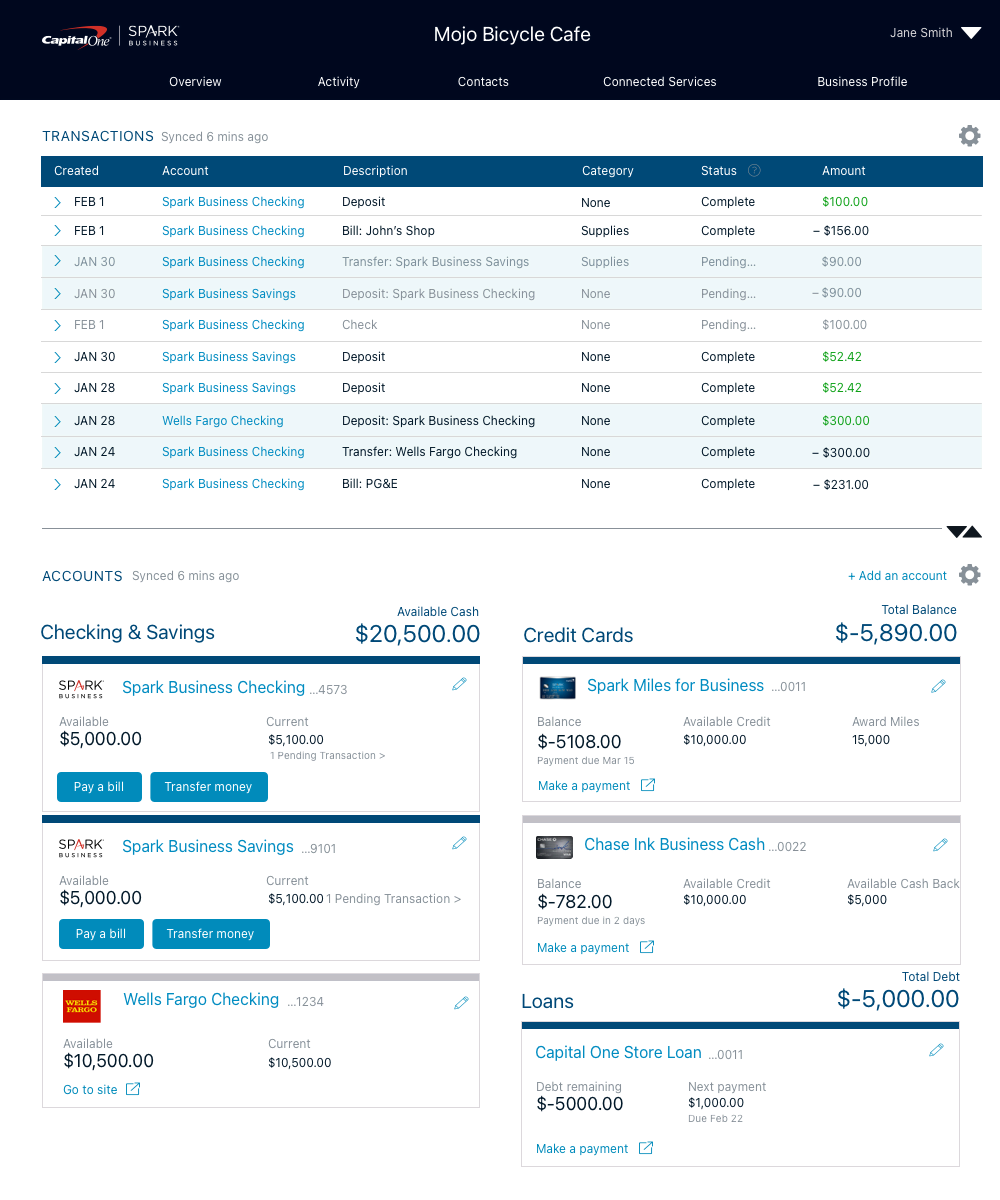
Research clearly showed that SMB owners operate with a near-term financial mental model.
They think in terms of immediate status and upcoming obligations, not abstract financial summaries.
The signed-in dashboard concept was designed around three core questions:
- How much cash do I have available right now?
- What are the most recent transactions I need to be aware of?
- What is the next bill I need to pay?
Rather than leading with product accounts, the dashboard answered those three questions first.
Visual Concepts
Impact & Outcomes
This work provided:
- A validated understanding of the Spark SMB audience
- Clear strategic directions for marketing positioning
- A signed-in dashboard aligned to real financial mental models
- Executive-ready concepts to guide internal decision-making